Guides
Fixed vs Reducing Balance Interest Explained
Two loans can quote the same rate and cost very different amounts. A worked example shows flat 12% costing Rs 82,148 more than reducing balance 12%.
Two loans can quote the same interest rate and cost very different amounts. The reason is usually how the interest is calculated: on the original amount you borrowed, or on what you still owe. That single difference changes the total enough that comparing rates alone can be actively misleading.
Flat rate and reducing balance: the core difference
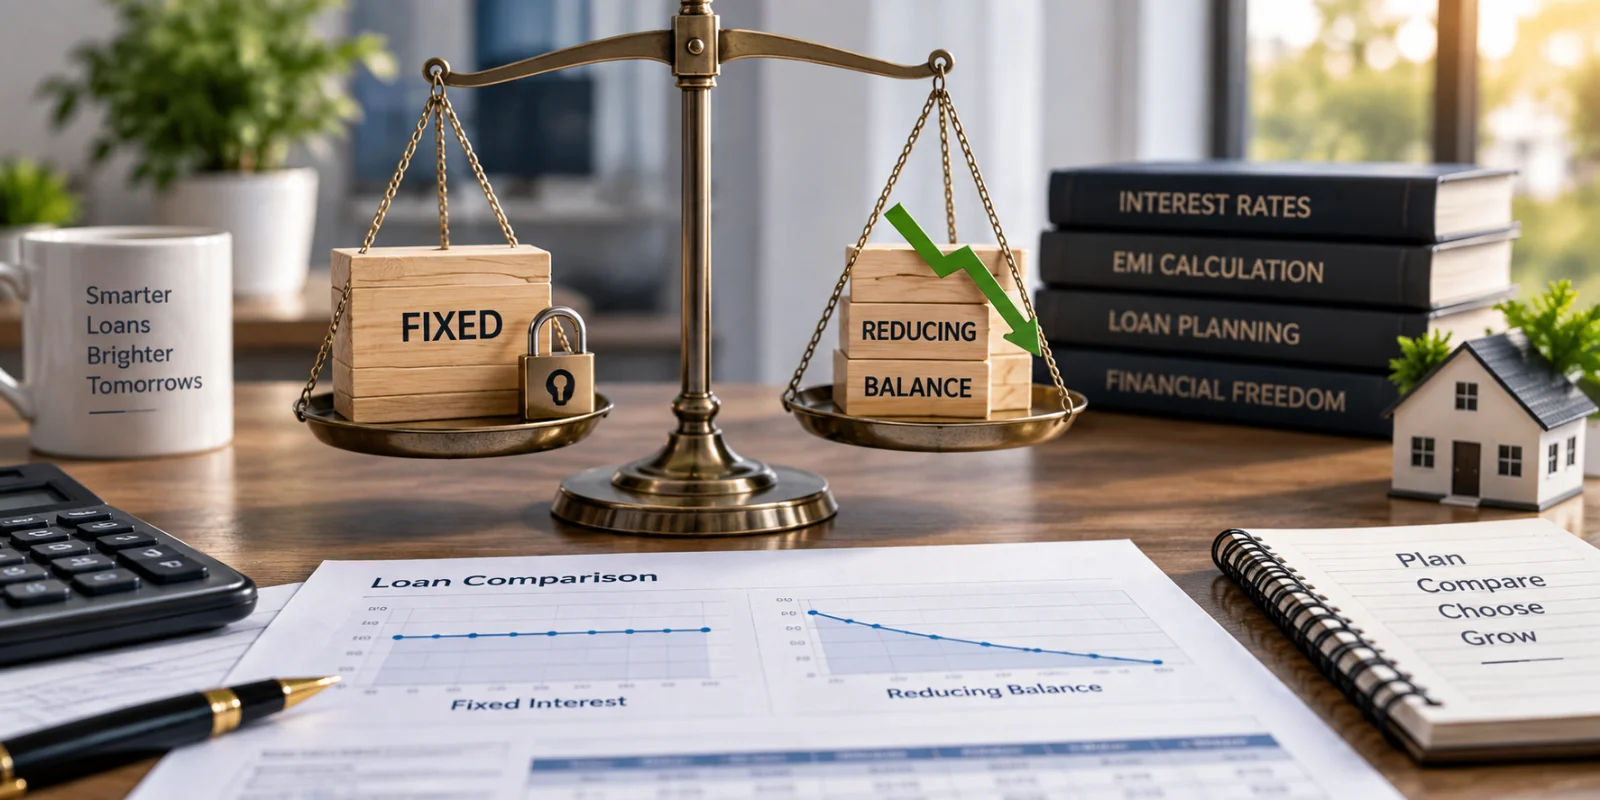
On a flat rate, interest is calculated on the full original principal for the entire tenure. You repay principal every month, but the interest charge does not notice — it keeps being worked out on the amount you started with.
On a reducing balance, interest is calculated on the outstanding amount. Every instalment lowers the principal, so the next month's interest is charged on a slightly smaller figure. The interest portion shrinks over the life of the loan.
Most retail lending in India — home loans, loans against property, most personal and business loans — is on a reducing balance. Flat rates still appear in some consumer, vehicle and short-term financing, and in informal lending.
Flat vs reducing balance: a worked comparison
The clearest way to see the difference is with real numbers. Take a loan of ₹5,00,000 over 3 years, quoted at 12% under each method:
| Flat rate 12% | Reducing balance 12% | |
|---|---|---|
| Monthly EMI | ₹18,889 | ₹16,607 |
| Total interest | ₹1,80,000 | ₹97,852 |
| Total repaid | ₹6,80,000 | ₹5,97,852 |
Same loan, same tenure, same quoted rate — and ₹82,148 more paid under the flat method. That is the whole of the difference, and it comes purely from how the interest is calculated.
What a flat rate is worth in reducing-balance terms
Turning the comparison around makes the gap starker. To produce the same ₹1,80,000 of interest on that loan, a reducing-balance rate would have to be around 21.2%. So a flat rate of 12% on a three-year loan is, in real terms, close to a 21% reducing-balance rate.
The multiple is not fixed — it widens with longer tenures — but the direction never changes, and the gap is always large rather than marginal. This is why a flat rate can look like the better offer when it is clearly the worse one. If one lender quotes flat and another quotes reducing balance, you are not comparing two prices. You are comparing two different things written in the same units.
These figures come from the same engine as our EMI calculator, which models reducing balance. Rupee amounts are rounded to the nearest rupee, and the example is an illustration rather than an offer.
This is why a flat rate can look like the better offer when it is the worse one. If one lender quotes a flat rate and another quotes reducing balance, you are not comparing two prices. You are comparing two different things that happen to be written in the same units.
How to compare them properly
Ignore the headline rate and compare one number: the total amount repaid over the full tenure. Every lender can tell you this, and it is the only figure that makes two different structures comparable.
- Ask each lender for the total repayment — principal plus all interest and charges — over the whole tenure.
- Ask whether the rate is flat or reducing balance, in those words. Do not infer it.
- Ask for the monthly instalment and the number of instalments, and multiply them as a cross-check.
- Ask what is excluded from that figure — processing fees, insurance, documentation charges.
- Compare the totals. The lower total is the cheaper loan, whatever the quoted rates say.
Our EMI calculator models reducing balance and shows the total repayment figure directly, along with the month-by-month split between interest and principal.
Monthly, quarterly and annual rests
Even within reducing balance there is a further distinction worth asking about: how often the outstanding balance is recalculated. This is called the rest.
- Monthly rest — the balance is updated every month, so each repayment starts reducing interest immediately.
- Quarterly or annual rest — the balance is updated less often, so repayments you have already made keep attracting interest until the next recalculation.
A monthly rest is the most borrower-friendly of the three. Two loans both described as "reducing balance" can differ on this point, so it is worth a direct question.
How prepayment interacts with each structure
This is where the difference becomes most visible. On a reducing-balance loan, paying extra reduces the outstanding principal, and every month of interest after that is calculated on the smaller figure — so the saving compounds for the rest of the tenure.
On a flat-rate loan, the interest for the whole tenure was effectively fixed at the start. Repaying early often saves far less than borrowers expect, and some flat-rate agreements calculate a settlement figure that includes a large part of the remaining interest anyway. If you expect to repay early, ask exactly how a foreclosure amount would be computed, in writing.
What to watch for in an offer
- A rate quoted with no basis stated. If the document does not say flat or reducing, ask until it does.
- An unusually low headline rate on a short-tenure consumer loan — a common place for flat rates to appear.
- A total repayment figure that is hard to obtain. It should be simple to provide.
- Fees quoted separately from the rate, which make the rate look lower than the true cost of borrowing.
- The rest frequency, where the loan is on reducing balance.
Frequently asked questions about flat and reducing balance rates
Which is better, flat or reducing balance?
At the same quoted percentage, reducing balance costs less, because interest is charged only on what you still owe. The caution is that the two are rarely quoted at the same percentage — a flat rate is usually quoted lower precisely because it is calculated differently. Compare total repayment rather than deciding on the structure alone.
How do I tell which one I am being offered?
Ask directly, and get the answer in the sanction letter rather than in conversation. A practical cross-check: multiply the monthly instalment by the number of instalments. Compare that total to the amount borrowed, and you have the real cost of the loan regardless of what the rate is called.
Are home loans flat or reducing balance?
Home loans in India are generally on a reducing balance, usually with a monthly rest. You should still confirm it for your specific offer rather than assume, along with whether the rate is fixed or floating — which is a separate question from flat versus reducing.
Is a reducing-balance loan always cheaper?
Not automatically. A reducing-balance loan at a high rate, over a long tenure, with heavy fees, can cost more than a well-priced alternative. The structure tells you how interest is computed; it does not by itself tell you the loan is good value. The total repayment figure does.
Does the EMI change on a reducing-balance loan?
On a fixed rate, the instalment stays the same — what changes is the split inside it, with the interest share falling and the principal share rising over time. On a floating rate, the instalment or the tenure can change when the benchmark moves, which is a separate mechanism.
The one question to ask
If you remember nothing else from this page: ask every lender for the total amount you will repay over the full tenure, and compare those figures. It cuts through flat versus reducing, rests, and most fee structures in a single question.
You can model a reducing-balance loan and see the total in the EMI calculator, or put two structures side by side with the loan comparison tool. If you would like help reading an offer you have received, getting in touch is an enquiry, not a loan application.
Have a question about what you just read?
An advisor can help you apply what you just read to your own situation.
- Free for you. Our advice costs you nothing. We are paid a commission by the lender once a loan is disbursed, never by you.
- We speak English, Hindi and Marathi.