Guides
How EMI Affects Your Monthly Budget
An EMI is better understood as a reduction in your monthly income than as an item of spending. Here is how to plan around one before you commit.
An EMI is a fixed amount leaving your account on the same date every month, for years. That regularity is what makes it easy to plan around — and also what makes it easy to underestimate. The question worth asking before you borrow is not "can I pay this instalment?" but "can I pay it in the month everything else goes wrong?"
What an EMI actually consists of
Each instalment covers two things: interest on what you still owe, and a repayment of some of the principal. The total stays the same, but the split shifts over the loan. Early instalments are mostly interest, because the outstanding balance is at its largest. Later ones are mostly principal.
This has a practical consequence people often meet by surprise. Three years into a long loan, you may have paid a substantial sum and reduced the outstanding balance by much less than you expected. Nothing has gone wrong — that is simply how a reducing-balance loan amortises. The EMI calculator shows the full schedule month by month, and the split is worth looking at before you commit rather than after.
How EMI affects your monthly budget
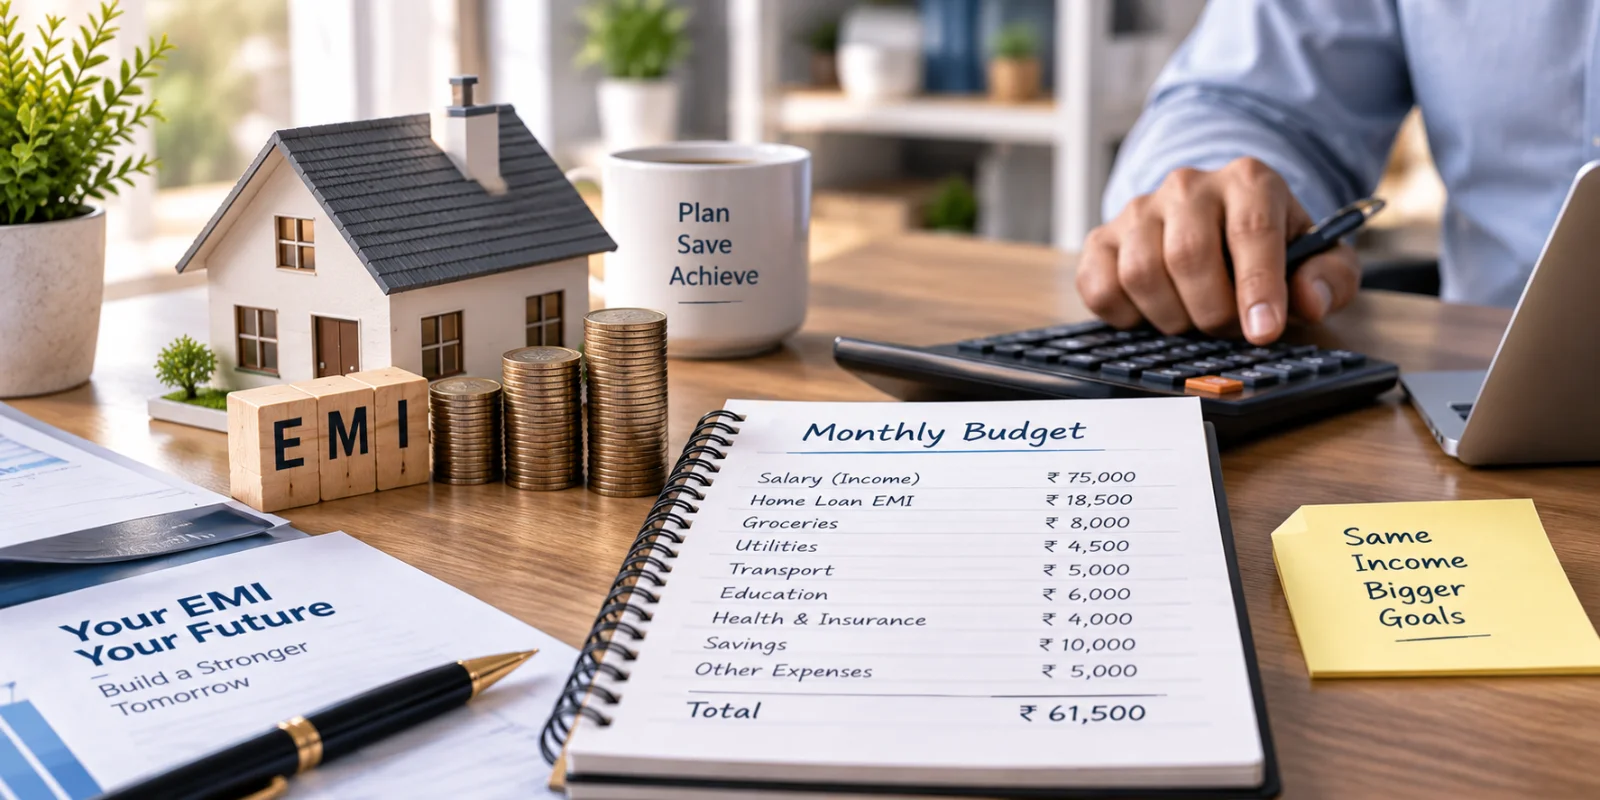
An EMI is different in kind from most other spending. Groceries flex. Eating out flexes. An EMI does not: the amount and the date are fixed by contract. So it is better understood as a reduction in your monthly income than as an item of expenditure.
A useful exercise is to re-draw your budget with the EMI taken off the top rather than added to the bottom. Subtract it from your income first, then see what the rest of your life has to run on. If that remaining figure looks tight on a normal month, it will not hold on an abnormal one.
What lenders look at, and why it is not enough
Lenders assess what proportion of your income already goes to repayments, and cap the new EMI so the total stays inside their comfort range. That calculation protects the lender, and it is a reasonable sanity check — but it is not a household budget.
It generally does not know about your rent if you are renting, school fees, support you provide to family, medical costs, insurance premiums paid annually, or the irregular expenses that land a few times a year. An approval tells you a lender is willing to lend. It does not tell you the instalment is comfortable.
Budgeting around an EMI: a practical method
- Work out your reliable monthly income. Take-home pay, not gross. If part of your income is variable — commission, bonus, freelance work — plan against the part you can count on.
- List every fixed commitment, including existing EMIs, rent, insurance and fees. Annual costs count: divide them by twelve.
- Subtract both from your income. What remains is what the new EMI and your living costs share.
- Leave genuine headroom. An EMI that consumes everything left over is one bad month from trouble.
- Test the instalment before you commit to it. Move that exact amount into a separate account on the same date for two or three months. If it pinches, you have learned something cheaply.
Why tenure is the most important number
Tenure is where most of the room to manoeuvre lives, and where the trade-off is sharpest. A longer tenure lowers the monthly instalment and raises the total interest paid. A shorter one does the reverse.
Neither is simply better. A short tenure saves interest only if you can actually sustain the higher instalment for the whole term; one missed payment costs more than the interest saved. A long tenure buys breathing room at a real price. The honest approach is to pick a tenure you can hold through a difficult year, not the one that produces the lowest total on a spreadsheet.
Model both in the EMI calculator and compare the total repayment figures, not only the monthly instalments.
The costs that sit outside the EMI
An EMI is not the whole cost of borrowing. Budget for these separately:
- Processing and documentation fees, usually payable up front.
- Insurance premiums, where cover is required or bundled.
- Valuation and legal fees on property-backed loans.
- Late payment charges, which apply from the day after the due date.
- Prepayment or foreclosure charges, if you expect to close the loan early.
And for a property purchase, the costs around the transaction — registration, stamp duty, moving, furnishing — often land in the same months as the first few instalments.
Building a buffer before the first instalment
The single most useful protection is a reserve covering several instalments, set aside before the loan starts rather than accumulated afterwards. It converts a job change, a medical month or a delayed payment from a credit-record problem into an inconvenience.
If building that reserve means borrowing less, or waiting, that is usually the better trade. The reserve protects the loan; the loan does not protect the reserve.
When your EMI can change
A fixed-rate loan keeps the same instalment throughout. A floating-rate loan does not: when the benchmark moves, the lender adjusts either your EMI or your tenure. Many lenders change the tenure first and leave the instalment alone, which keeps your monthly budget intact but quietly extends how long you are paying.
Either way it is worth knowing which lever your lender pulls, and checking the outstanding balance and remaining tenure once a year rather than assuming they are tracking your original schedule. Our guide on how repo rate changes affect your EMI covers the mechanics.
Frequently asked questions about EMI and budgeting
How much of my income should go to EMIs?
There is no single correct figure, and any specific percentage is a rule of thumb rather than a rule. What matters more is what is left after every fixed commitment is met, and whether that remainder absorbs a bad month. Two people with identical incomes and identical EMIs can be in very different positions depending on rent, dependants and existing obligations.
Should I choose a longer tenure to reduce my EMI?
It is a legitimate choice, but it is a trade rather than a saving: you pay less each month and more in total. A longer tenure makes sense if the lower instalment is what makes the loan genuinely sustainable. It makes less sense if it is being used to borrow more than you otherwise could.
Does paying extra each month help?
Usually yes, because the extra reduces the outstanding principal, which reduces the interest charged from then on. How your lender applies it varies — some shorten the tenure, some reduce the instalment — and charges or notice periods may apply. Confirm the treatment with your lender before relying on it, and model it in the calculator's prepayment planner.
What happens if I miss one EMI?
Expect a late payment charge, and expect the missed payment to be reported to the credit bureaus. A single lapse that you correct quickly is not the same as a pattern, but it does leave a record that affects future borrowing. If you can see a difficult month coming, talking to the lender before the due date is far better than after it.
Can I change my EMI date?
Many lenders allow it, often to align the instalment with your salary credit, which is a sensible thing to request. Policies and any charges differ, so ask at the application stage when it is simplest to arrange.
Before you decide the amount
Work out the instalment you can sustain first, then let that decide how much you borrow — not the other way round. The EMI calculator turns an amount into an instalment, the affordability planner works backwards from what your budget can carry, and the eligibility planner gives an indicative range. All three are planning models, not offers. If you would rather talk it through, getting in touch is an enquiry, not a loan application.
Have a question about what you just read?
An advisor can help you apply what you just read to your own situation.
- Free for you. Our advice costs you nothing. We are paid a commission by the lender once a loan is disbursed, never by you.
- We speak English, Hindi and Marathi.